How to reduce your homeowners insurance premiums

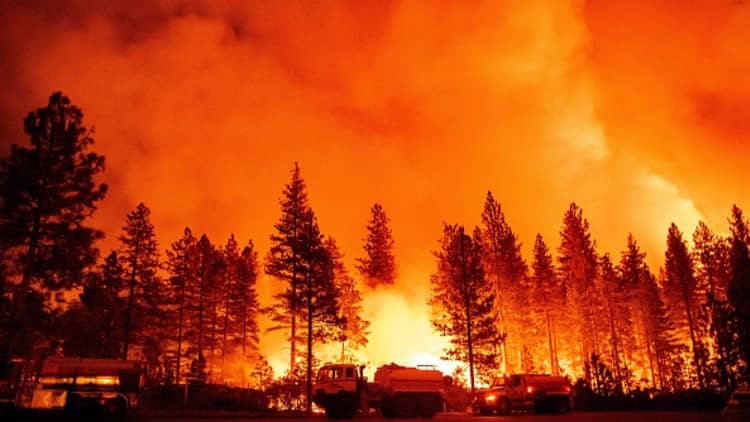
Residents watch as a wildfire moves down hill at Runkle Canyon Park in Simi Valley, California, on May 19, 2026.
Kayla Bartkowski | Los Angeles Times | Getty Images
Homeowners insurance costs have risen sharply for many people in the United States in recent years.
Policyholders looking to lower their premiums have some relatively simple options, according to insurance experts. Other maneuvers require a financial investment that could save money in the long run, they said.
Average insurance premiums rose 24% between 2021 and 2024, to $3,303 annually, according to a report released last year by the Consumer Federation of America, a consumer advocacy group.
This roughly corresponds to the pace of U.S. inflation during that period, according to consumer price index data. US Treasury Department, a analysis The report, published last year, found that average policy premiums were 8.7% above the inflation rate from 2018 to 2022.
Residents of some states pay much more than average. For example, average premiums in Louisiana and Nebraska exceeding $500 per monthThat’s more than $6,000 a year, according to a February report from Bankrate.
Experts say premiums are increasing due to inflation associated with the repair and reconstruction of homes; climate change, which increases the frequency and severity of storms and wildfires; reinsurance rates; and migration of homeowners to riskier areas.
According to insurance experts, there are some ways homeowners can try to lower their premiums or keep them from rising so quickly.
1. Strengthen your home
A damaged roof in North Harbor, Florida, on June 20, 2023.
Thomas Simonetti for Washington Post via Getty Images
While homeowners can’t control the weather — or the frequency and severity of natural disasters — they do have more control over how resilient their homes are to hurricanes, wildfires and other events, said Peter Kochenburger, an insurance expert and adjunct law professor at Southern University Law Center.
Efforts to mitigate the hazard include the addition of storm shutters; strengthening a roof to protect against hail, wind, or wildfires; and experts said, for example, that a house should be strengthened to better withstand an earthquake.
These improvements can help lower insurance premiums because they reduce the risk of damage to one’s home, experts said. For example, renovating a home to withstand hurricane-force winds saves property owners an average of $6 for every $1 invested, according to a 2019 study. to work By the National Institute of Building Sciences.
“Unfortunately, all of this costs money,” said Amy Bach, co-founder and chief executive of United Policyholders, a consumer advocacy group for insurance policyholders.
Roofing and vents with fire-resistant features typically cost more than $5,800, while the cost of renovating an existing roof to be wildfire resistant can exceed $22,000; based on The 2025 report cited Laura Hausman, a senior housing policy analyst at the Bipartisan Policy Center, a nonpartisan think tank, from 2018. predictions By Headwaters Economics.
The cost of installing hurricane shutters can range from $13,000 to $19,000, Hausman wrote. Project costs can vary widely depending on property size, location, materials and contractors, he wrote.
Some states, including Alabama, California, Colorado and Louisiana, offer grants to homeowners to cover the cost of mitigation efforts, Hausman wrote.
There are also relatively inexpensive things some homeowners can do, such as installing humidity sensors that can help detect leaks more quickly, Bach said.
There’s no guarantee that insurance companies will lower premiums for homeowners who undergo mitigation projects, Hausman wrote, so policyholders “should carefully research their insurance company’s and their county’s policies.” In some states, insurance companies are required to reduce premiums for certain upgrades.
Before starting a project, ask your insurer which home improvements are eligible for deductibles. based on To Liberty Mutual Insurance’s March post.
Also remember: Depending on your insurer, some home improvements, such as additions to your home, can add value and therefore increase your insurance rates.
2. Increase your deductible
A scene from the Siena Homes project in Winchester, California, on Tuesday, May 26, 2026.
Robert Gauthier | Los Angeles Times | Getty Images
A policy deductible is the amount a homeowner will owe out-of-pocket before the insurance company begins paying compensation for a claim.
Experts said increasing one’s deductible is one way to lower monthly premiums.
Bach recommends that people carry the highest deductible they can afford and also consider how affordable that deductible is in the event of costly home damage. Homeowners must pay the full deductible out of pocket before insurance coverage kicks in; so make sure you have enough savings to cover major damages.
Most insurance companies recommend a deductible of at least $500, according to the Insurance Information Institute, an insurance industry group. Increasing someone’s deductible to $1,000 could save up to 25% on premiums, he said.
3. Avoid ‘small’ claims
Although it may seem counterintuitive, policyholders should avoid making insurance claims for any damage to their homes, Bach said.
“Don’t make small claims,” he said.
Bach said landlords should try to keep their records “as clean and clear as possible.”

For example, he recommends avoiding making an insurance claim for less than the deductible if possible. He said insurers won’t pay any benefits in such cases, and each claim could lead to higher premiums.
“Do what you can to maintain your insurance for major losses you cannot cover yourself,” Bach said. “Because each claim could put you in a higher risk category and cause you to pay more.”
4. Don’t pay more than you need
Policyholders should also make sure they don’t purchase more insurance than they need.
“Take a look at your policy limits and the value of your home and belongings every year.” based on To the National Association of Realtors, a real estate industry group. “Some items are depreciable and may not need as much coverage.”
For example, if a fur coat that originally cost $5,000 is no longer worth that much, policyholders may reduce or cancel a “floater,” a policy add-on that fully covers certain valuables, to lower premiums, according to the Insurance Information Institute.
Additionally, according to NAR, homeowners should keep in mind that they are covering the renovation cost, not the market value of the home.
According to the institute, “The land beneath your home is not at risk from theft, storms, fire, and other perils covered by your homeowner’s policy.” “So don’t take the value of the insurance into account when deciding how much homeowners insurance to buy. If you do, you’ll end up paying a higher premium than you should.”
5. Create strategy for insurers
Vladimir Vladimirov | E+ | Getty Images
Choosing an insurance company wisely can save homeowners some money.
For example, some companies that sell homeowners, auto and liability policies will take 5% to 15% off your premium if you purchase two or more policies, according to the Insurance Information Institute.
However, it was stated that policy holders should ensure that the package price is lower than the price of purchasing separate policies from different insurance companies.
According to the institute, they may also receive discounts for staying with the same insurance company for many years. It was stated that some insurance companies reduced their premiums by 5 percent for policyholders who stayed with them for three to five years and by 10 percent for those who stayed with them for six years or more.
Homeowners can consult consumer guides, insurance agents, companies and online insurance quote services to help them shop, according to the institute. Experts recommend shopping around periodically to check for better prices elsewhere. For some homeowners, the savings can be $2,000 or more per year, according to a recent NerdWallet to work.
Beyond price, homeowners should also consider service quality if making a request. The National Association of Insurance Commissioners, a regulatory group, has information to help choose an insurance company, including complaints.
6. Improve your credit
Having a good credit score can help lower insurance premiums because insurers often use credit scores. Credit-based insurance scores to determine policy costs, according to the National Association of Realtors.
Paying lenders on time and reducing credit utilization are among the ways homeowners can improve their credit scores.
7. Consider insurance when buying a home
Sign outside new homes in the Rosemary Grove community by Taylor Morrison in Vacaville, California, USA on Wednesday, October 8, 2025.
David Paul Morris | Bloomberg | Getty Images
Experts said that homeowners can be better served by taking insurance costs into consideration when purchasing a home.
For one thing, there are “some areas where people shouldn’t live,” such as coastlines, said Kochenburger of the Southern University Law Center.
Of course, this doesn’t deter many buyers.
For example, U.S. counties with the highest wildfire risk saw 446,000 more people migrate in 2021 and 2022 than in 2023, a 51% increase over the two-year period from 2019 to 2020. analysis by Redfin.
States including Florida, Texas and Arizona “exploded in popularity during this period despite increased risks of storms, droughts, wildfires and extreme heat” as people sought more affordable housing, warmer weather and lower taxes and increased opportunities to work from home, according to Redfin.
Besides avoiding lower-risk areas to live, there are other steps homeowners can take, experts said.
According to the Insurance Information Institute, “You may pay less for insurance if you buy a home near a fire hydrant or in a community with a professional fire department rather than a volunteer fire department.” “If your home’s electrical, heating and plumbing systems are less than 10 years old, it may be cheaper. If you live in the East, consider a brick home because it is more wind resistant. If you live in an earthquake-prone area, look for a wood-frame home because it is more likely to withstand such disasters.”
It has been stated that choosing “wisely” can reduce premiums by 5 percent to 15 percent.
Experts said it is important to remember that living in certain areas may require additional types of insurance.
For example, standard homeowners policies generally do not cover flood or earthquake damage and may therefore require people to purchase separate policies for these risks.
According to the institute, homeowners can check the Comprehensive Loss Insurance Exchange, or CLUE, report of the home they are considering to get a snapshot of the property’s insurance claims history; this can help identify some of the home’s insurance-related risks.